Excess / Umbrella Liability Insurance
Excess and umbrella liability insurance adds higher limits when a serious claim outgrows your base policies. Compare top-rated carriers and structure limits that satisfy contracts without overpaying.
Partnered with 100+ carriers to help you find the best value.
Your base policy has a limit. A lawsuit does not.
One severe accident, injury, or lawsuit can push damages above your underlying policy limits. When that happens, the remaining amount can become an out-of-pocket problem for the business. Excess coverage and umbrella liability are designed to pick up where your general liability, commercial auto, and other underlying policies stop, so one bad day does not become a balance-sheet event.

How do you compare excess and umbrella quotes in one place?
Excess and umbrella liability insurance quotes depend on your underlying carriers, industry class, loss history, payroll and revenue, and what limits you need to meet. Terms also vary by carrier, including required underlying minimums, attachment points, aggregates, and exclusions that can matter more than a small price difference.
Infinite shops multiple A-rated markets and lays the offers out side by side so you can compare what you are actually buying, not just the premium. We flag underlying requirements and gaps up front, so the limit you purchase will respond the way you expect when a claim pierces your base policy.
Excess vs. umbrella. There is a difference.
Excess and umbrella liability insurance are often grouped together, but they solve slightly different problems. Excess liability typically follows the exact terms of an underlying policy and simply adds more limit above it. Umbrella liability can sometimes broaden coverage and may respond differently depending on the form, including how it handles certain claims and defense costs.
Infinite helps you choose the right structure for your program, confirm the underlying schedule meets carrier requirements, and avoid surprises where the umbrella is assumed to respond but the wording says otherwise.
Do your contracts require higher limits than your base policy carries?
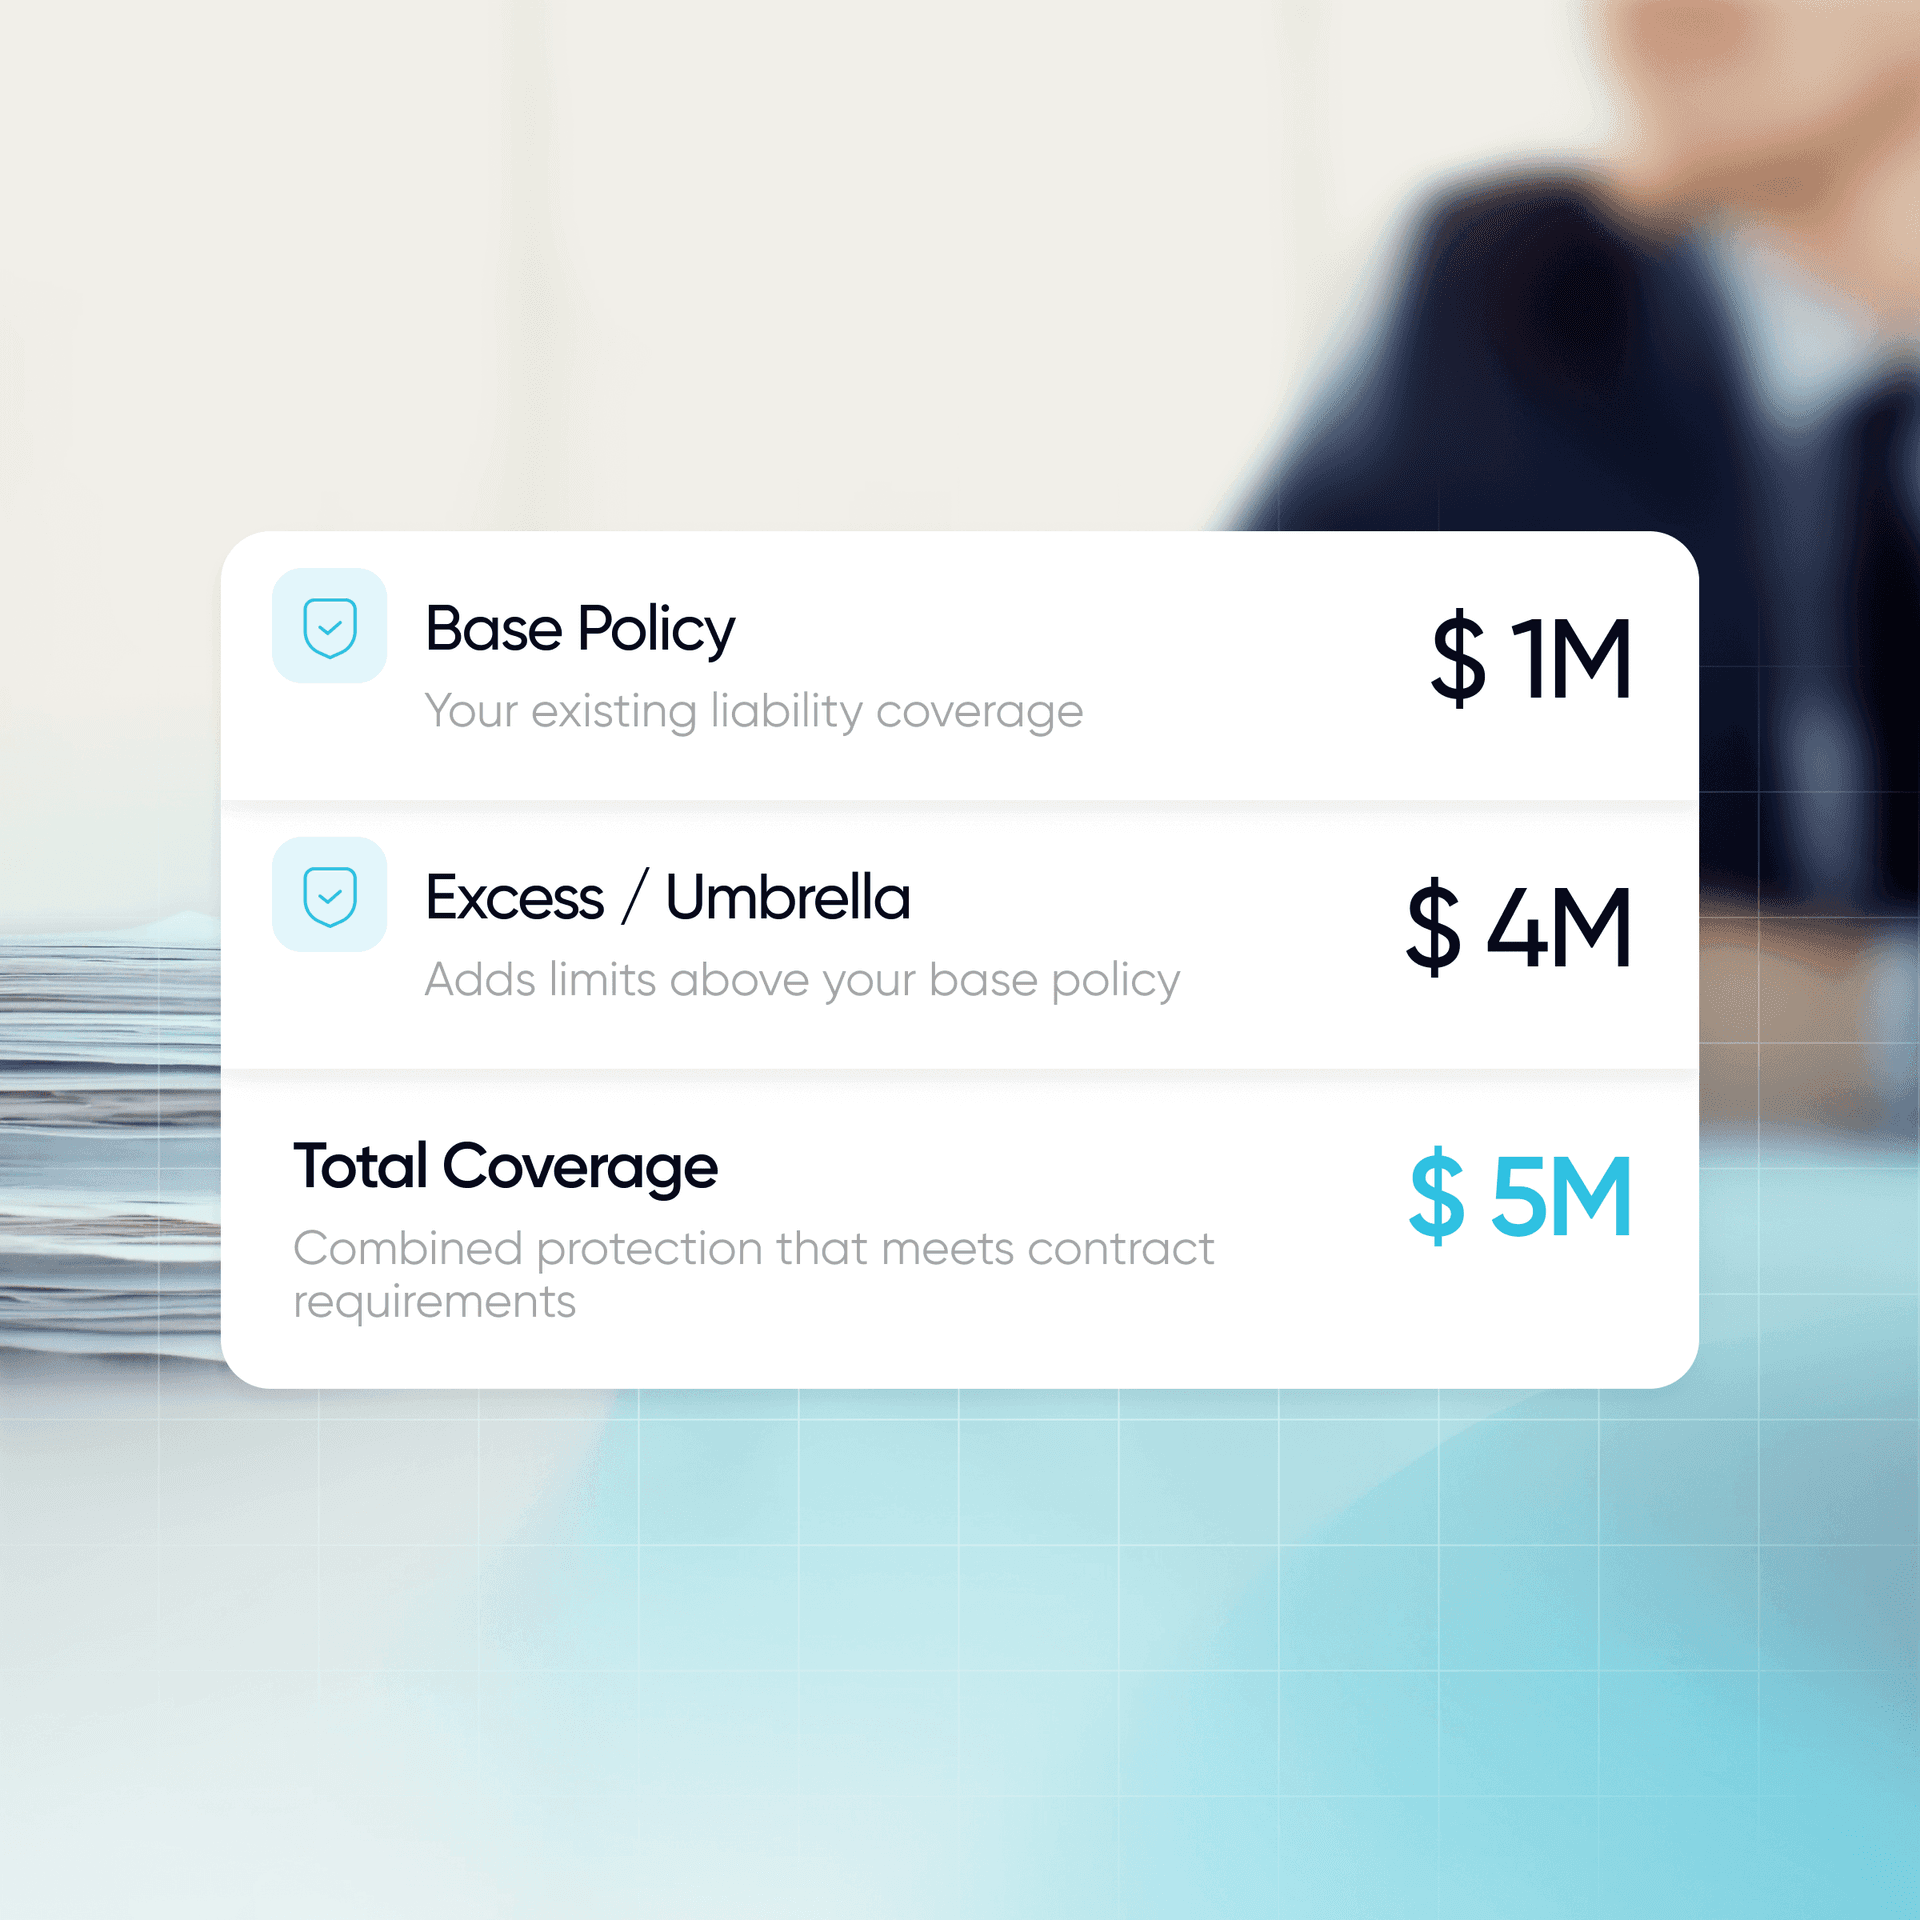
Many landlords, clients, and vendor agreements require $2M, $5M, or more in liability limits before they will sign. If your general liability or auto policy is at $1M, you can be contract-ready by stacking higher limits on top, without rewriting your entire insurance program.
Infinite reviews contract language, verifies the required underlying coverages, and builds a limit structure that satisfies the requirement cleanly. We also help keep certificates and endorsements consistent with what your counterparties expect so deals do not stall.
The more policies underneath, the more your excess carrier matters.
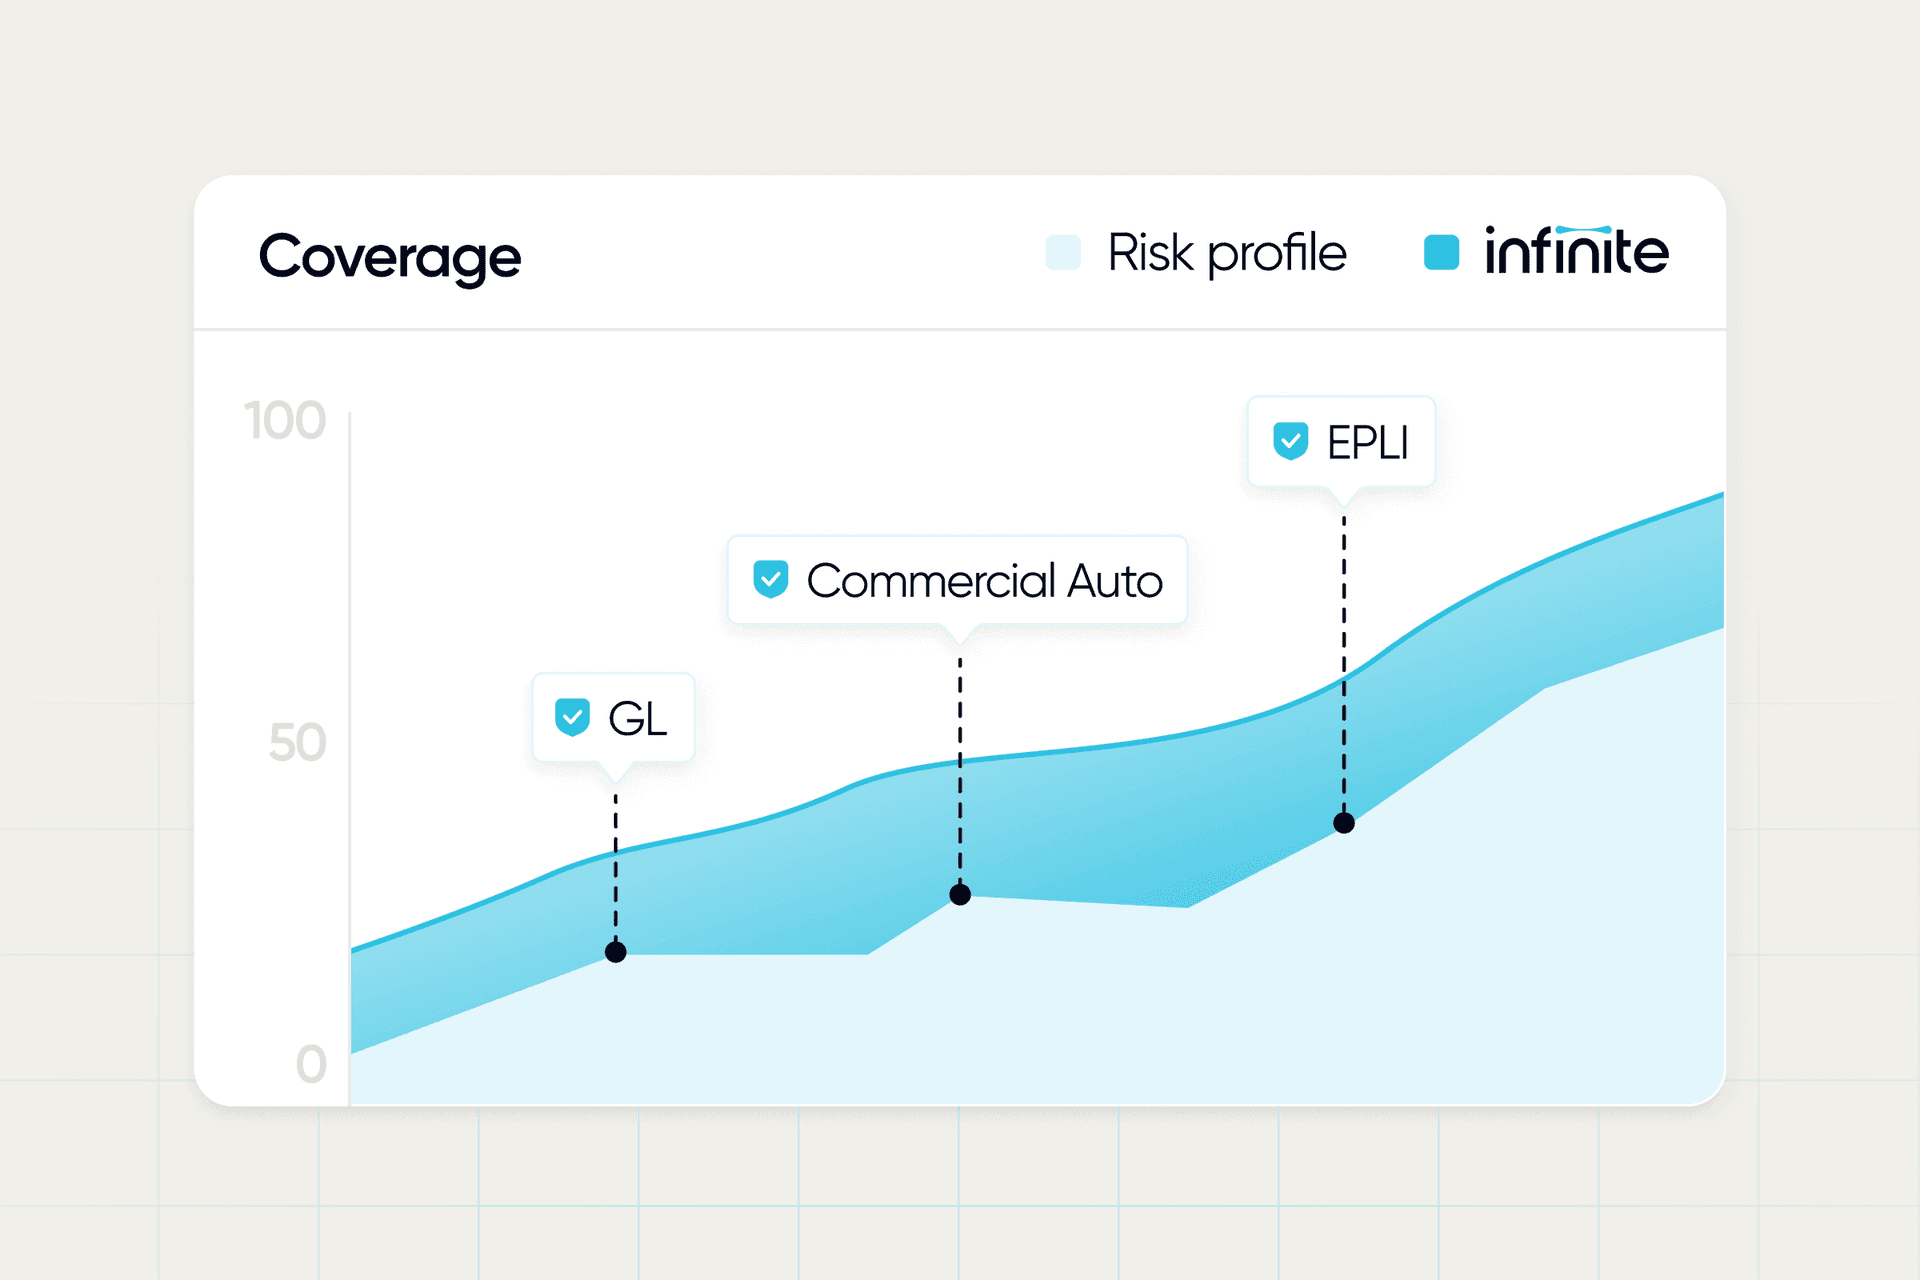
If you carry multiple underlying lines, like general liability, commercial auto, employers liability, and EPLI, the excess layer has to sit correctly over all of them. Mismatched terms, inconsistent exclusions, or missing underlying limits can create friction at claim time.
Infinite coordinates the full stack, aligns renewal timing and carrier requirements, and checks for gaps between layers so your excess program is built to respond when multiple policies are in play.
Why businesses rely on Infinite when limits get serious.
Real reviews on clear program structure, contract-ready paperwork, and guidance that holds up when claims get complicated.
QUESTIONS & ANSWERS
FAQ
Have Questions? Talk to Us
By submitting, you agree to our Privacy Policy and Terms of Service.